
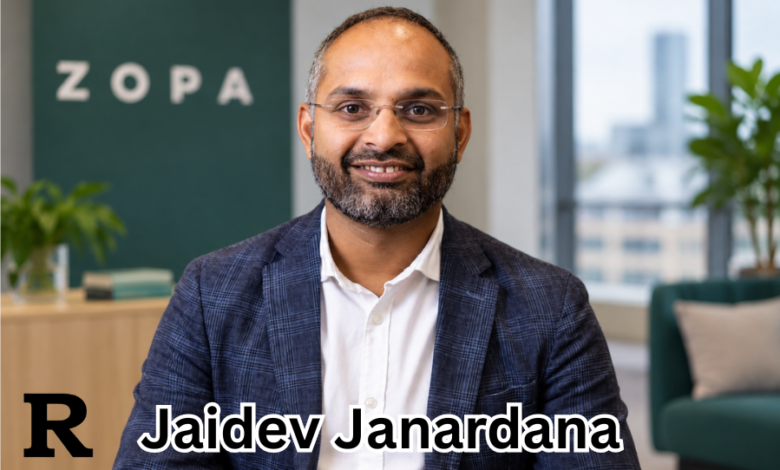
Jaidev Janardana has become a notable figure in British digital banking through a career built around consumer credit, risk management and financial technology. As Group Chief Executive Officer of Zopa, he has overseen the company’s shift from its peer-to-peer lending origins into a fully licensed digital bank serving a broad UK customer base.
He joined Zopa in 2014, became CEO in 2015 and later guided the business through banking authorisation, the launch of Zopa Bank, the closure of its original retail P2P investment operation and expansion into savings, cards, loans, current accounts and investments.
Quick Bio
| Field | Details |
|---|---|
| Full Name | Jaidev Janardana |
| Profession | Business Executive, Banker, Fintech Leader |
| Known For | Group CEO of Zopa |
| Current Position | Group Chief Executive Officer, Zopa |
| Joined Zopa | October 2014 |
| Became CEO | August 2015 |
| Previous Company | Capital One |
| Previous Roles | Chief Credit Officer, Chief Marketing Officer |
| Education | B.Tech, Gujarat University; MBA, Indian Institute of Management Bangalore |
| Industry | Banking, Fintech, Consumer Finance |
| Based In | United Kingdom |
| Major Achievement | Led Zopa’s transition from P2P lending to a fully licensed digital bank |
| Net Worth | Not publicly verified |
| Nationality | British business executive; reliable public profiles focus primarily on his professional career |
From Consumer Credit to Fintech Leadership
Before Zopa, Janardana spent 12 years at Capital One. He joined the company in 2002 in McLean, Virginia, working initially on the US credit card business, before moving to the UK in 2007.
The move placed him in a demanding part of consumer finance at a difficult moment. As Chief Credit Officer for Capital One’s UK operation, he managed credit risk through the global financial crisis, when lenders faced deteriorating economic conditions, changing borrower behaviour and intense scrutiny of underwriting.
He later became Chief Marketing Officer. Zopa’s executive biography credits him with helping return Capital One’s UK business to profitability and growth. His experience across credit, marketing, customer acquisition and risk provided a broad foundation for fintech leadership.
The Move That Put Him at the Centre of Zopa
Janardana joined Zopa in October 2014 as Chief Operating Officer. At the time, the company was best known as a pioneer of peer-to-peer lending, connecting borrowers and investors through an online platform.
His COO responsibilities included marketing, technology, credit risk and customer service. In August 2015, less than a year after joining, he was appointed Chief Executive Officer, succeeding co-founder Giles Andrews. Reuters reported that Zopa had arranged more than £750 million of lending.
Peer-to-peer lending had established Zopa’s identity, but digital financial services were widening rapidly. Challenger banks were building app-based consumer relationships, while regulators and investors were increasingly focused on the durability of fintech business models.
Turning a P2P Pioneer Into a Regulated Bank
The defining chapter of Janardana’s Zopa career has been the transformation into a bank.
Zopa secured its full UK banking licence in 2020 and launched Zopa Bank that June. The new operation initially sat alongside the existing P2P business and introduced products including fixed-term savings and credit cards, while drawing on Zopa’s long experience in lending and analytics.
It could accept deposits, build a broader range of financial products and develop deeper customer relationships. It also brought capital, prudential and operational requirements.
In December 2021, Zopa announced that it would close its retail peer-to-peer investing business after 16 years and focus fully on banking. Investor portfolios were transferred at full value, with Zopa explaining that the bank offered greater scope to serve customers across a wider range of financial needs.
A company that helped popularise P2P lending in Britain chose regulated digital banking as the platform for its next stage while seeking to retain the speed and data-led approach associated with fintech.
Building Zopa Beyond Its Lending Roots
Under Janardana, Zopa has expanded into personal loans, credit cards, car finance, savings, current accounts and investments.
The scale of the business has risen with that broader product range. Zopa reported that in 2025 it reached 1.7 million customers, generated £377.1 million in revenue and held £6.4 billion in deposits. Loans on its balance sheet rose to £3.8 billion, while the company reported £65 million in underlying profit before tax and described 2025 as its third full year of profitability.
Zopa’s roots in credit underwriting gave it established lending economics, while deposits added another source of funding as the bank scaled.
The launch of Biscuit, Zopa’s current account, also moved the company further into everyday banking. Current accounts can deepen relationships by sitting closer to customers’ daily spending, saving and money management.
Why His Risk Background Still Matters
Janardana’s leadership combines fintech expansion with traditional credit discipline.
Consumer lending can grow quickly in favourable conditions, but weak underwriting can lead to substantial losses when borrowers come under pressure. His experience managing credit during the financial crisis helps explain why risk, analytics and lending discipline have remained central to Zopa’s strategy.
This differentiates Zopa from a model based mainly on rapid customer acquisition. The bank has pursued digital convenience while also emphasising credit economics, regulation and profitability.
Investors now expect digital financial companies to demonstrate sustainable margins, operational resilience and credible long-term economics alongside customer growth.
Education and Professional Foundations
Professional profiles identify Janardana as holding an MBA from the Indian Institute of Management Bangalore and a B.Tech from Gujarat University. A Salzburg Global profile updated in 2026 lists the same qualifications.
Some older biographies describe parts of his education differently, so it is safer to rely on the qualifications that appear consistently across recognised professional profiles.
His combination of technology and management education fits the career that followed. Modern consumer finance increasingly depends on data, software, marketing, regulation and credit decision-making, all areas that have featured in his senior roles.
A Wider Role in UK Fintech
Janardana’s profile extends beyond Zopa. He has participated in initiatives associated with Innovate Finance and has been listed as a member of its Unicorn Council for UK FinTech, formed to contribute recommendations on the conditions needed for British fintech businesses to scale.
Access to growth capital, regulation, public markets and international competitiveness remain major issues for the UK fintech sector.
Zopa has also supported collaborative financial education initiatives, reinforcing its effort to present itself as a broader financial-services brand rather than simply a specialist lender.
European Expansion and the Next Stage
By 2026, the strategic discussion around Zopa had moved beyond proving that the digital bank could become profitable.
In March 2026, Janardana said Zopa was considering acquisitions that could provide an entry point into Northern Europe, including possible opportunities in Germany or Scandinavia. He also emphasised that the UK remained the company’s main focus.
Future growth could come from winning a larger share of existing customers’ financial activity, launching additional products or selectively expanding beyond Britain.
For Janardana, the job is therefore different from the one he took on in 2015. He is no longer leading only a P2P lender. He is managing a profitable, regulated financial group that must preserve its fintech identity while operating with the disciplines expected of a bank.
Personal Life and Net Worth
Janardana keeps a relatively low public profile outside his professional work. Reliable sources focus mainly on his banking career, education and industry views rather than his family or private life, so unsupported personal details should not be treated as fact.
There is also no widely established, authoritative estimate of Jaidev Janardana’s personal net worth. Zopa’s revenue, deposits, funding rounds or company value cannot be used as substitutes for his individual wealth. Without verified information on compensation, ownership interests and private assets, any precise figure would be speculative.
Conclusion
Jaidev Janardana’s career at Zopa is closely tied to one of the more significant transformations in British fintech. He joined when the company was identified mainly with peer-to-peer lending and later led it into regulated banking, a broader consumer product range and sustained profitability.
His earlier experience in credit risk and marketing at Capital One remains relevant as Zopa scales. With the company now operating as an established digital banking challenger and considering opportunities beyond its home market, Janardana’s role has evolved from leading a fintech pioneer to managing a growing financial group competing more directly with mainstream banks.
FAQs.
What is Jaidev Janardana known for?
Jaidev Janardana is best known as the Group Chief Executive Officer of Zopa. He has led the business through its transformation from a peer-to-peer lending pioneer into a fully licensed UK digital bank offering lending, savings, cards and everyday banking products.
When did Jaidev Janardana become CEO of Zopa?
He became Zopa’s CEO in August 2015 after joining the company as Chief Operating Officer in October 2014. He succeeded Zopa co-founder Giles Andrews, who moved into an executive chairman role.
Where did Jaidev Janardana work before Zopa?
Before joining Zopa, Janardana spent about 12 years at Capital One in the United States and United Kingdom. His senior roles included Chief Credit Officer for the UK business and later Chief Marketing Officer.
What did Jaidev Janardana study?
Professional profiles list an MBA from the Indian Institute of Management Bangalore and a B.Tech from Gujarat University. Some older biographies differ on additional educational details, so those two qualifications are the most consistently documented.
What is Jaidev Janardana’s net worth?
There is no reliable, publicly verified figure for his personal net worth. Zopa’s financial performance or valuation should not be treated as a measure of Janardana’s own wealth.
READ THIS TOO: John Peace: The Business Leader Behind Experian, Burberry and a Midlands Legacy


One Comment